

Loan Calc Hub
by AppDsgnur
4.2
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.2
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
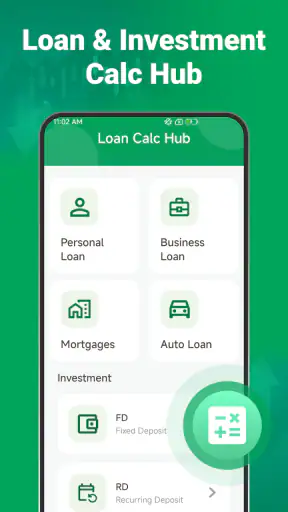
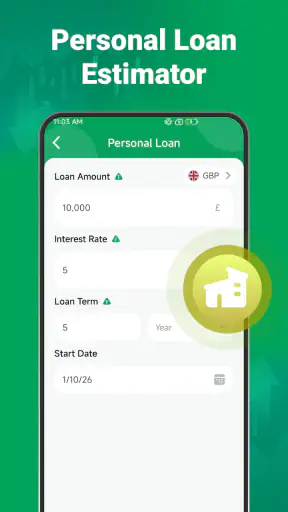
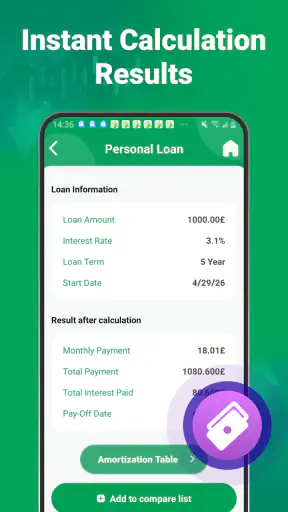
 Analysis by Getfullapps
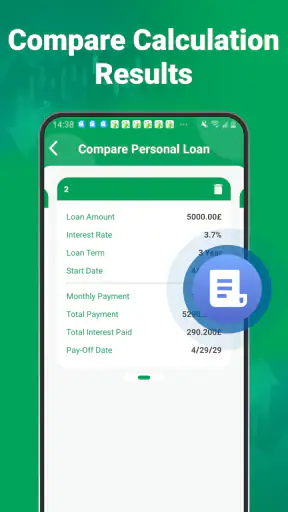
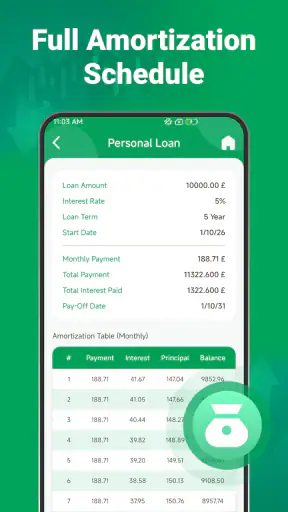
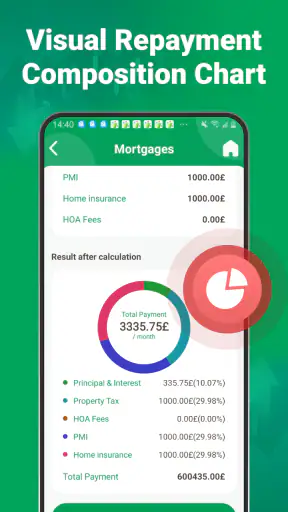
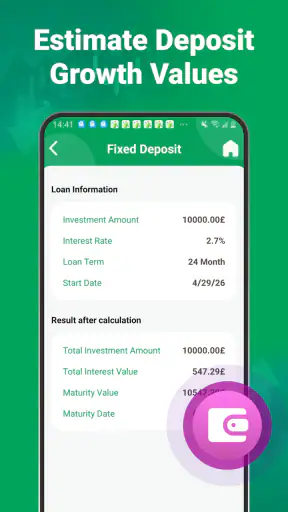
I approached Loan Calc Hub as a practical money-planning tool rather than something to open casually. It is a free finance app from AppDsgnur that brings several common calculations into one place: loan repayments, fixed-deposit estimates, and recurring-investment projections. That combination makes sense for anyone who wants a quick comparison before speaking with a bank, lender, or investment provider, but the usefulness depends heavily on entering sensible assumptions and reading the result carefully.
My first impression is that the app is aimed at reducing the small amount of arithmetic that often slows down an otherwise simple decision. Instead of building a spreadsheet every time I want to compare a borrowing option with a savings plan, I can use a dedicated calculator and focus on the inputs. It is currently listed as version 1.1.0.0, works on Android 9 and later, and is rated for Everyone, which fits its straightforward personal-finance purpose.
The app has already reached over a million installs and holds a 4.2 average from roughly seven hundred ratings. Those figures suggest that it has found an audience among people looking for quick financial estimates, although they should not be treated as proof that every result will match a particular bank or investment provider. A calculator can be useful and still require careful checking, especially when real contracts include fees, taxes, changing rates, or rules that a general-purpose tool may not model.
Where the experience usually gets stuck
When I reach this point, the usual sticking point is not the arithmetic but deciding whether the inputs describe the same product I am comparing. A quoted rate can sit alongside fees, timing rules, or repayment conventions that change the real outcome. I find it helpful to pause before recalculating and first identify which assumption might be different; the next section focuses on checks that make that starting point clearer.
The difficult part is choosing the right interpretation
Most friction with a calculator like this does not come from pressing the calculation button. It comes earlier, when I have to decide what a number means. A loan amount, interest rate, and repayment period sound clear until I compare offers that use different compounding conventions, repayment frequencies, or additional charges. If I enter a monthly rate where the screen expects an annual one, the result may look perfectly reasonable while being completely unsuitable for the decision I am making.
That is why I would not use the first result as an answer to “Can I afford this?” I would use it as a controlled estimate. The monthly figure can help me compare scenarios, but affordability also depends on insurance, processing charges, late-payment rules, taxes, and my existing commitments. Those surrounding costs are often more important than a small difference in the calculated repayment.
The fixed-deposit section has a similar trap. The maturity estimate is only as meaningful as the rate, term, deposit amount, and interest treatment I enter. A quoted rate may be annual while the institution calculates returns under its own schedule. If the provider deducts tax or applies different rules for early withdrawal, the app’s figure should be read as a planning baseline rather than a guaranteed payout.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Recurring investment estimates need disciplined assumptions
Recurring-investment calculations are especially easy to overread because a projected final amount can feel more certain than it is. I would treat the output as a scenario built around an assumed return, not as a promise. Markets do not deliver a smooth return every period, and even a conservative-looking assumption can create an unrealistic impression if the time horizon is long.
A useful habit is to run several versions instead of relying on one optimistic input. I might compare a cautious return with a middle estimate and then a stronger scenario, while keeping the contribution and period unchanged. The important insight is not the largest number on the screen; it is how sensitive the outcome is when the assumption changes. If a small rate adjustment produces a large difference, that is a reason to remain cautious, not a reason to chase the higher projection.
Input errors can look like app problems
When a result seems strange, I first check the units and the scale of each entry. I look for an extra zero in the principal, an accidental decimal, a period entered in the wrong unit, or a rate copied from an offer without checking whether it is annual. I also clear the scenario mentally and enter a simple test case again rather than repeatedly editing a complicated set of figures.
This is one of the most useful ways to work with Loan Calc Hub: change one input at a time. If I alter the amount, rate, and duration together, I cannot tell which value caused the unexpected result. A controlled sequence makes the calculator easier to trust because I can see whether the output moves in the direction I expect. A larger loan should not produce a smaller repayment under the same assumptions, and a longer period should not be interpreted as automatically cheaper overall.
Why the first screen can feel less helpful than expected
A focused calculator is convenient, but it does not replace a full financial dashboard. Someone expecting account tracking, bill reminders, document storage, lender comparisons, or a complete investment portfolio may find the experience narrow. Its strength is the calculation itself, not the management of every step that follows.
I also think users can become stuck when they expect the app to explain the financial meaning of every result. A number without context is not enough. I still need to understand whether the repayment is principal plus interest, whether a maturity estimate includes deductions, and whether a recurring-investment projection assumes reinvestment. The safest approach is to use the displayed result as a starting point for questions, then compare it with the wording from the actual provider.
Setup checks that prevent avoidable confusion
Before entering figures, I like to make the scenario easy to audit rather than relying on memory or copying numbers from several offers at once. Separating the amount, rate, and time period—and keeping their source together—helps me avoid mixing terms that look similar but belong to different products. With that groundwork in place, I can troubleshoot a surprising result without turning the exercise into guesswork.
Start with a clean scenario
Before entering figures, I write down what I am trying to compare. For a loan, that might be the amount I need, the advertised rate, and the repayment period. For a fixed deposit, I note the initial deposit, quoted return, and maturity term. For a recurring investment, I separate the regular contribution from the expected return and the investment duration. This short preparation prevents me from mixing values from different products in one calculation.
I would also keep the source of each number nearby. If a lender gives one rate in an advertisement and another in a formal quotation, I use the figure that belongs to the product I am actually evaluating. The same applies to deposits and investment plans. Loan Calc Hub can calculate the scenario I enter, but it cannot know which rate is applicable to my personal eligibility or which conditions are attached to an offer.
Check the time and rate conventions
The most important setup check is consistency. I make sure the interest-rate format and the time period match the labels in the relevant calculator. I do not assume that a percentage copied from a website can be pasted without interpretation. If the app asks for a yearly rate, I use the yearly figure; if it presents a period in months, I do not silently convert it to years unless the interface clearly expects that.
When a provider uses a different compounding method from the calculator, I record that difference beside the result. This simple note stops me from presenting an estimate as if it were an official quotation. It also makes later troubleshooting easier: if the app and the bank disagree, I can compare the assumptions rather than blaming the first number that looks different.
Use the minimum necessary personal information
For a calculation, I would enter only the financial values needed for that calculation. There is no practical reason to type sensitive account credentials, card details, identity numbers, or private banking information into a calculator workflow. A loan estimate can be built from general amounts and terms, while a deposit or recurring-investment estimate can be tested with rounded figures before I decide whether the product deserves closer attention.
This approach also makes comparisons cleaner. I can test a hypothetical amount first, then replace it with a more realistic figure once I understand the result. It is easier to spot an input mistake in a simple scenario than in a detailed one that contains unnecessary personal information.
Prepare a comparison note outside the app
One practical limitation of a focused calculator is that a single result does not automatically become a decision record. I keep a short note with the scenario name, the inputs, the displayed result, and the date I checked the provider’s offer. That lets me compare two loans or two savings choices without relying on memory.
I would not copy only the final repayment amount. I also record the rate and term that produced it. Otherwise, a lower monthly figure can look better even when it comes from a much longer period and creates a higher total cost. This is a small workflow improvement, but it turns a quick calculation into something I can review later with less confusion.
Recovering a workflow when the result looks wrong
When an estimate still seems off, I treat recovery as a step-by-step comparison, not a hunt for a button that will produce a preferred answer. A simple test scenario can show whether the issue is an entry or a mismatch between the calculator’s assumptions and a provider’s terms. That distinction matters because a correct calculation can still be the wrong basis for a real decision; next, I consider other causes of disagreement.
Reset the scenario before changing everything
If the output looks implausible, I start again with one simple set of figures. I avoid making a long chain of corrections because it becomes impossible to know whether the issue was an input, a unit, or my interpretation of the result. A clean retry is usually faster than trying to repair a scenario whose assumptions have become unclear.
I then change one value at a time and watch the direction of the result. This is a basic but powerful check. If increasing the borrowed amount lowers the repayment, or if extending the term produces a result that does not fit the rest of the inputs, I stop and inspect the fields again. The point is not to force the answer I expect; it is to identify which assumption needs clarification.
Separate calculation recovery from financial interpretation
There are two different problems that users often combine. The first is whether the app has accepted the values and produced a calculation. The second is whether the calculation represents the real financial product. Re-entering figures can help with the first problem, but it cannot resolve a mismatch in compounding, fees, tax treatment, or eligibility.
For example, if Loan Calc Hub shows a different repayment from a lender’s quotation, I would place the two sets of assumptions side by side. I would check the principal, rate type, term, repayment frequency, and extra charges before deciding that either result is incorrect. Often the difference is not a malfunction; it is two calculations describing slightly different products.
Use scenarios instead of repeated guesses
When I am deciding whether a loan fits my budget, I prefer a small range of scenarios. I might calculate the target amount, a slightly lower amount, and a longer or shorter term, then compare the monthly burden with the total repayment. This reveals a trade-off that a single calculation hides: reducing the monthly payment can increase the overall cost because interest continues for longer.
For recurring investments, I use the same method but focus on uncertainty. I compare different assumed returns and contribution levels rather than treating one projected maturity value as a target. The workflow is more honest when the app is used to show a range of possible outcomes. It also helps me decide whether the plan remains comfortable if I contribute less than expected or if returns are weaker.
Know when to stop troubleshooting the interface
If the same simple scenario produces an unexpected result after I have checked the units and entered the figures again, I stop escalating the complexity. I do not add more assumptions to compensate for an unexplained output. At that point, I would compare the calculation with a trusted manual formula or an official provider estimate, and I would treat the app as a convenience rather than the final authority.
This is not a criticism unique to Loan Calc Hub. Any compact finance calculator has a boundary between what it can calculate and what it can explain. The responsible response is to isolate the question, verify the assumptions, and avoid making a financial commitment based solely on a number that I cannot interpret.
When the app is not the cause
A result can differ from an offer even when the calculation itself is behaving as expected, because providers may define rates, charges, and schedules in their own ways. I also keep the wider household budget and the uncertainty of investment returns in view rather than treating a single output as a decision. The final section looks at how those outside factors should shape the way I use the estimate.
Provider rules can explain a mismatch
A bank or investment provider may use rules that are not reflected in a general calculator. A lender can add fees, apply a different interest convention, or structure repayments in a way that changes the total. A fixed-deposit provider may calculate returns according to its own schedule and apply deductions at maturity. An investment product may display a projection based on assumptions that are not the same as the rate I entered.
In each case, the app may be doing exactly what I asked while the product is doing something more complicated. The right comparison is not simply “which final number is bigger?” I compare the definitions behind the numbers and ask what I will actually pay or receive. This is where the app is most useful as a conversation aid: it gives me a baseline and helps me identify the questions that need answers.
Affordability is broader than repayment
A calculated loan repayment does not include every pressure on a household budget. I also consider rent, utilities, existing debt, irregular expenses, and a reserve for emergencies. A repayment that fits during a good month may be uncomfortable when income changes or an unexpected bill arrives.
Loan Calc Hub is therefore best used before a budget review, not instead of one. I can use the result to test a borrowing limit, but I still need to look at the full monthly picture. If the app makes a loan appear affordable only when I choose an unusually long term, that is a warning to reconsider the borrowing amount rather than an invitation to stretch the schedule.
Investment projections are not risk assessments
The recurring-investment calculation can show how contributions and an assumed return interact, but it does not tell me whether an investment is suitable. It does not replace research into volatility, access to the money, charges, or the possibility of losing value. Someone who needs the money on a fixed date should be especially careful about treating a projection as an expected outcome.
For that reason, I would choose this app for early planning and comparison, while using a regulated provider’s documents for the final decision. If I need portfolio analysis, risk profiling, tax planning, or transaction management, a dedicated investment service or advice from a qualified professional is a better fit.
Who benefits most from this focused tool
I think Loan Calc Hub suits students, first-time borrowers, families comparing a few repayment options, and savers who want a quick estimate before opening a deposit. It is also useful for someone preparing questions for a bank appointment. The ability to move between borrowing, fixed-deposit, and recurring-investment scenarios encourages a broader comparison: I can ask whether taking on debt makes more sense than delaying a purchase, or whether a regular saving habit is realistic.
It is less suitable for users who want an all-in-one financial record, automatic account connections, detailed investment analytics, or formal lending advice. Those needs call for a more specialized product. I would also avoid relying on it alone for a high-value financial commitment where small differences in fees or calculation methods could materially change the outcome.
My practical verdict after using it as a planning companion
Loan Calc Hub succeeds when I treat it as a fast, focused calculator and not as a financial adviser. Its free access lowers the barrier to testing ideas, and its combination of loan, fixed-deposit, and recurring-investment calculations is more useful than having three unrelated tools for basic comparisons. The Everyone rating and support for Android 9 and later also make it approachable for a broad range of users.
The main weakness is not that it calculates too little; it is that a clean number can encourage too much confidence. I have to supply the context myself. I need to check whether the rate is comparable, whether fees are included, whether the term is expressed correctly, and whether a projected return is being mistaken for a promise. That extra discipline is essential in any finance app, but it matters particularly when the interface is designed to make results appear quickly.
My recommended workflow is simple: define the scenario, enter only the necessary figures, change one assumption at a time, and save the inputs beside the result. Then compare the estimate with the provider’s actual terms. If the numbers disagree, investigate the assumptions before assuming the app is broken. If the result still cannot be explained, do not use it to make the decision.
My bottom line is that this is a useful first-pass finance calculator, not a substitute for product documents or personal budgeting. I would keep it for quick loan comparisons and rough savings projections, especially when I want to understand how a change in amount, rate, or duration affects the outcome. I would skip it as my main financial tool if I needed account management, investment-risk analysis, or exact provider-specific calculations. Used with that boundary in mind, AppDsgnur’s app is a practical way to turn vague money questions into clearer scenarios.
Pros
- User-friendly interface for quick calculations.
- Supports multiple loan types and currencies.
- Detailed breakdown of monthly payments.
- Customizable interest rates and terms.
- No ads in the premium version.
Cons
- Limited features in the free version.
- No integration with financial apps.
- Occasional lag on older devices.
- Requires internet for updates.
- No dark mode available.
FAQs for Loan Calc Hub
What is Loan Calc Hub and how does it work?
Loan Calc Hub is a comprehensive financial application designed to simplify the process of managing and calculating loans. It allows users to input various loan details such as principal amount, interest rate, and loan term to generate detailed repayment schedules. This feature is particularly helpful for those who want to plan their finances effectively.
Is Loan Calc Hub free to use, or are there any subscription fees?
Loan Calc Hub offers a free version with basic features, but for advanced functionalities such as custom loan scenarios and ad-free experience, users can opt for a premium subscription. Pricing details and the specific features included in each plan can be found within the app’s settings or on their official website.
How accurate are the loan calculations provided by Loan Calc Hub?
The app uses industry-standard formulas to ensure high accuracy in its calculations. However, users should double-check with their financial institutions, as different banks may have varying policies and additional fees that could affect the final loan cost. The app serves as a reliable guide but not a definitive calculator.
Can Loan Calc Hub handle different types of loans?
Yes, Loan Calc Hub is versatile and supports a variety of loan types, including personal, auto, and home loans. Users can customize the input fields to match specific loan conditions, making it a flexible tool for different financial scenarios. This adaptability is one of its key strengths.
Is my personal information safe when using Loan Calc Hub?
Loan Calc Hub prioritizes user privacy and employs robust encryption methods to protect personal data. The app only requires minimal information necessary for calculations and does not store sensitive data on external servers. Users are encouraged to review the app’s privacy policy for detailed information on data protection measures.

Loan Calc Hub
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via dsgnur@gmail.com, visit https://pdfviewerplus.com, or review their https://sites.google.com/view/loan-calc-hub-privacy.










